📊 Executive Summary: How Interest Rates Shape Outcomes for Home Sellers
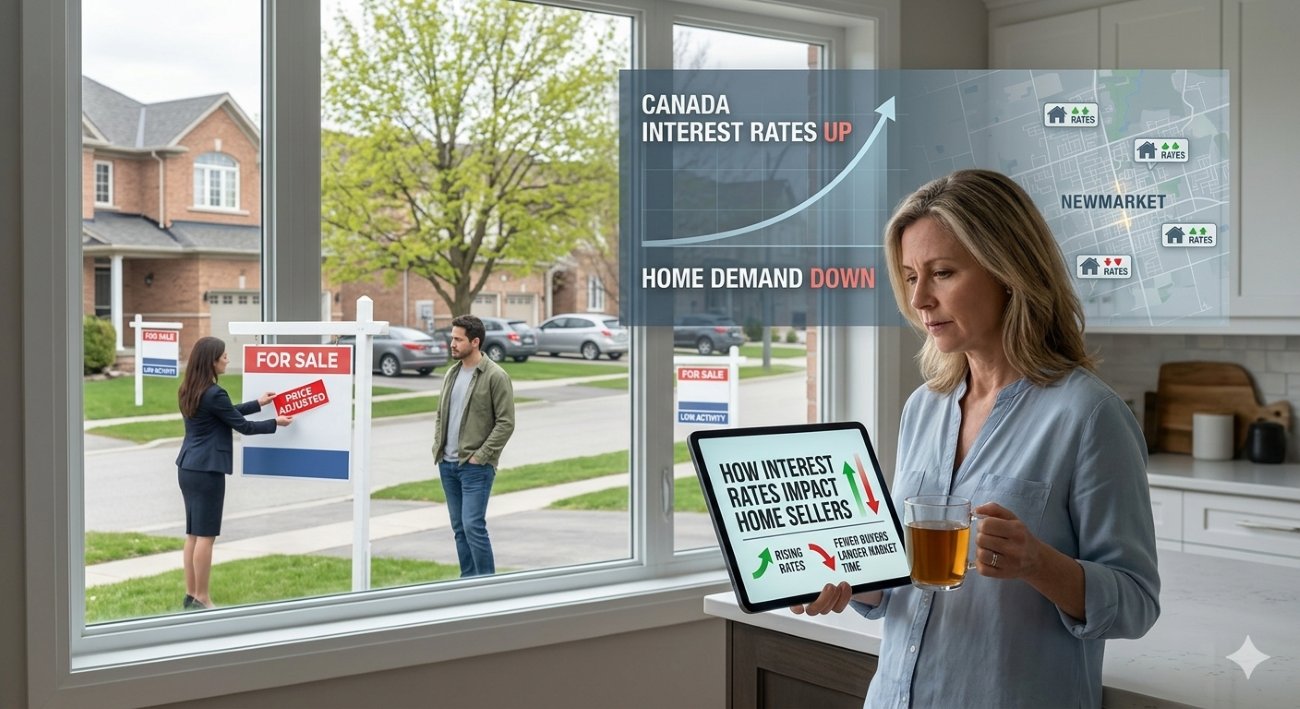
Interest rates are one of the strongest forces shaping what your home will sell for, how long it will take to sell, and how many qualified buyers you'll attract. When borrowing costs rise, fewer buyers can afford today's prices; when rates fall or stabilize, demand often returns and competition picks up.
As of early 2026, the Bank of Canada has held its policy rate at 2.25% — signalling a pause after a volatile cycle of hikes and inflation-fighting measures. According to CMHC, the rapid run-up in rates since 2022 created a significant "affordability shock," especially for buyers renewing mortgages or entering the market for the first time.
Put simply: you don't control interest rates, but they absolutely control your leverage as a seller — whether you're downsizing, moving up, or repositioning an investment property in Southern Ontario.
📚 Interest Rates 101 for Home Sellers
What's the Difference Between Policy Rate and Mortgage Rates?
The Bank of Canada sets a policy interest rate (the overnight rate) that influences the entire financial system. When this rate changes, banks reprice their prime rate and the mortgage products they offer.
- Variable-rate mortgages move closely with the Bank of Canada's prime rate — almost immediately.
- Fixed-rate mortgages follow bond yields, which react to expectations about future Bank of Canada decisions and inflation.
This means a policy rate decision in Ottawa eventually shows up as a higher or lower mortgage payment for buyers walking through your front door at a showing.
Why Small Rate Changes Hit Sellers Hard
Even a 1% change in mortgage rates can significantly alter what buyers can pay while staying within the federal stress test and their own comfort level. CMHC and major Canadian bank economists have documented how the rate increases since 2022 have pushed renewing borrowers into substantially higher monthly payments, while new buyers face stricter qualifying conditions.
🌡️ How Different Rate Environments Impact Home Sellers
- Larger buyer pool qualifies
- Multiple offers more likely
- Shorter days on market
- Stronger pricing power
- Emotional buying supports price
- Predictable buyer behaviour
- Local data drives pricing
- Less urgency, more strategy
- Balanced negotiations
- Accurate pricing matters most
- Buyer demand drops
- Longer days on market
- More conditional offers
- Price sensitivity increases
- Stress test pushes budgets lower
Over-supplied condo markets in parts of Toronto can struggle even in low-rate environments — and strong, well-priced detached homes in York Region can still sell quickly even when rates are elevated. Local fundamentals always matter alongside the headline rate.
📊 Rate Environment Comparison Table
| Rate Environment | Buyer Demand | Days on Market | Pricing Power | Seller Leverage |
|---|---|---|---|---|
| Low / Falling | High — more qualified buyers | Typically short in high-demand areas | Strong; multiple offers common | High — selective on price & terms |
| Stable | Moderate — driven by fundamentals | Varies by neighbourhood & segment | Balanced — pricing accuracy critical | Mixed — depends on local inventory |
| High / Rising | Weaker — buyers pushed to lower price brackets | Longer — especially at higher price points | Softer — more price sensitivity | Lower — buyers have more choices |
💡 How Interest Rates Affect Seller Decisions
1. Pricing Strategy
Interest rates directly shape which price bands buyers search in. When rates rise, Ontario sellers often find the "sweet spot" for pricing shifts downward as buyers' maximum budgets shrink. In higher-rate environments, it can sometimes be strategic to list slightly below the top of your valuation range to capture more search traffic and generate competition — rather than overpricing and chasing the market with reductions.
The market doesn't care what your neighbour sold for last year. It cares what a qualified buyer can afford right now.
2. Timing the Market
Upcoming Bank of Canada rate announcements, seasonal demand patterns (spring still dominates Ontario real estate), and local inventory levels all influence when to list. Sellers may consider listing before a widely expected rate hike, or waiting until after a cut or string of holds when sentiment and affordability are improving.
However, experts consistently emphasize that personal timelines — job moves, family changes, financial needs — should not be ignored in favour of pure rate speculation. A well-priced, well-presented home can sell in any environment; the strategy simply needs to reflect current borrowing conditions.
3. Financing Conditions & Appraisals
Higher rates and stress-test levels make it harder for some buyers to qualify and increase the risk that offers fall through at the financing stage. CMHC has noted that many borrowers renewing or applying today are absorbing noticeably higher costs, which can tighten lender underwriting and widen the gap between desired and approved mortgage amounts.
4. Move-Up vs. Downsizing Sellers
If you're selling and buying in the same market, interest rates hit you on both sides. Move-up sellers might benefit from demand for their entry-level or mid-range property but face higher carrying costs on the more expensive home they're purchasing. Downsizers may accept a softer price on their current home in a high-rate environment but enjoy a smaller, more manageable mortgage — or no mortgage at all — on their next property.
CMHC's work on renewal risk underlines why many owners need professional advice when deciding whether to stay put, refinance, or transact in a changing rate cycle.
🗺️ Regional Breakdown Across Southern Ontario
York Region (Newmarket · Aurora · Vaughan)
Deepak's Primary MarketBalanced market in 2026. Detached homes seeing longer days on market in upper price ranges, but well-priced properties in desirable communities still attract qualified buyers.
Peel Region (Mississauga · Brampton)
West GTAStrong underlying demand but affordability pressure rising with sustained higher rates. Townhomes and semi-detached outperforming higher-end detached.
Durham Region
East GTAMore affordable entry points keep this market relatively active. First-time buyers still present, though stress-test pressure is real.
Toronto (GTA Core)
Central GTAHigh sensitivity to rate changes. The condo market is more affected than detached, with oversupply in some downtown segments still a factor.
Waterloo Region (Kitchener · Waterloo)
Waterloo RegionRelatively stable due to strong tech employment base and university-driven demand. Rate sensitivity lower than in pure residential markets.
Hamilton-Burlington
Hamilton AreaMixed performance depending on price point. Luxury segment hit harder by high rates; entry-level more resilient.
Property Type Sensitivity
| Property Type | Rate Sensitivity | 2026 Trend |
|---|---|---|
| Detached Homes | High | Slower demand in higher price ranges; strategy-dependent |
| Semi-Detached | Moderate | Still relatively active across most Ontario markets |
| Townhomes | Low–Moderate | Strong demand; best value per dollar for buyers |
| Condos | High | Oversupply in some areas; longer days on market |
🧠 Market Sentiment & Seller Psychology
Rising rates tend to increase uncertainty for both buyers and sellers. CMHC and other analysts have noted that higher payments, renewal shocks, and a cooling economy weigh on consumer confidence — making households more cautious. Sellers may worry about "missing the peak," delay listing while waiting for Bank of Canada clarity, or become more willing to negotiate when showings slow.
Conversely, periods of rate cuts or clear pauses can improve sentiment. RBC and CMHC analysis has suggested that lower or stabilizing borrowing costs, combined with strong immigration and limited supply, can eventually bring buyers back and create upward pressure on prices in markets like Ontario. This shift is often visible first in showing activity and offer volume before it appears in headline price data.
Understanding that psychology — not just the numbers — helps set realistic expectations about how quickly buyers will move and how aggressively they'll negotiate in each phase of the rate cycle.
🔑 Actionable Strategy for Sellers in 2026
Price Within Buyer Affordability Bands
Use current mortgage rate levels and typical qualification ranges to estimate where the deepest buyer pools sit in your area — whether that's $700K–$900K in parts of the GTA or a different band in secondary markets. Pricing within these "affordability lanes" generates stronger interest and better offers.
Make Your Property Stand Out
In slower markets, the homes that sell are the ones that stand out on quality and presentation. Strategic pre-listing improvements, professional staging, and strong photography/video ensure qualified buyers choose to view and offer on your property first.
Be Flexible on Terms
Be open to reasonable financing and home-inspection conditions. Negotiate closing dates that align with buyers' renewals or sale of their own home. Flexibility can be as important as price in a rate-sensitive market.
Get Financial Clarity Early
Speak with both a mortgage professional and your Realtor before listing. Understand your net proceeds, your next purchase affordability, and any renewal risks. Waiting until the last minute is how expensive mistakes happen.
❓ FAQ: Interest Rates & Home Sellers in Ontario
🏆 How Deepak Raj Realtor Helps Sellers Win in Any Market
In a market where interest rates change the rules every few months, home sellers need more than a sign on the lawn — they need a data-driven strategy that connects Bank of Canada decisions to what's happening on their specific street.
Deepak Raj Realtor combines local Southern Ontario experience — with a focus on Newmarket, Aurora, and across York Region — with up-to-date analysis of mortgage rates, stress-test impacts, and CMHC and bank research to calibrate pricing and marketing for each listing. In markets like York Region, small pricing and strategy adjustments can mean tens of thousands of dollars difference. That's not marketing talk — that's math.
Whether you're downsizing, moving up, or repositioning an investment property, the right guidance can turn a complex interest-rate environment into an opportunity rather than a threat.

 Data provided by the Ontario Regional Technology & Information Systems. The information is deemed reliable, but is not guaranteed. Not intended to solicit buyers or sellers, landlords or tenants currently under contract.
The trademarks REALTOR®, REALTORS® and the REALTOR® logo are controlled by The Canadian Real Estate Association (CREA) and identify real estate professionals who are members of CREA. The trademarks MLS®, Multiple Listing Service® and the associated logos are owned