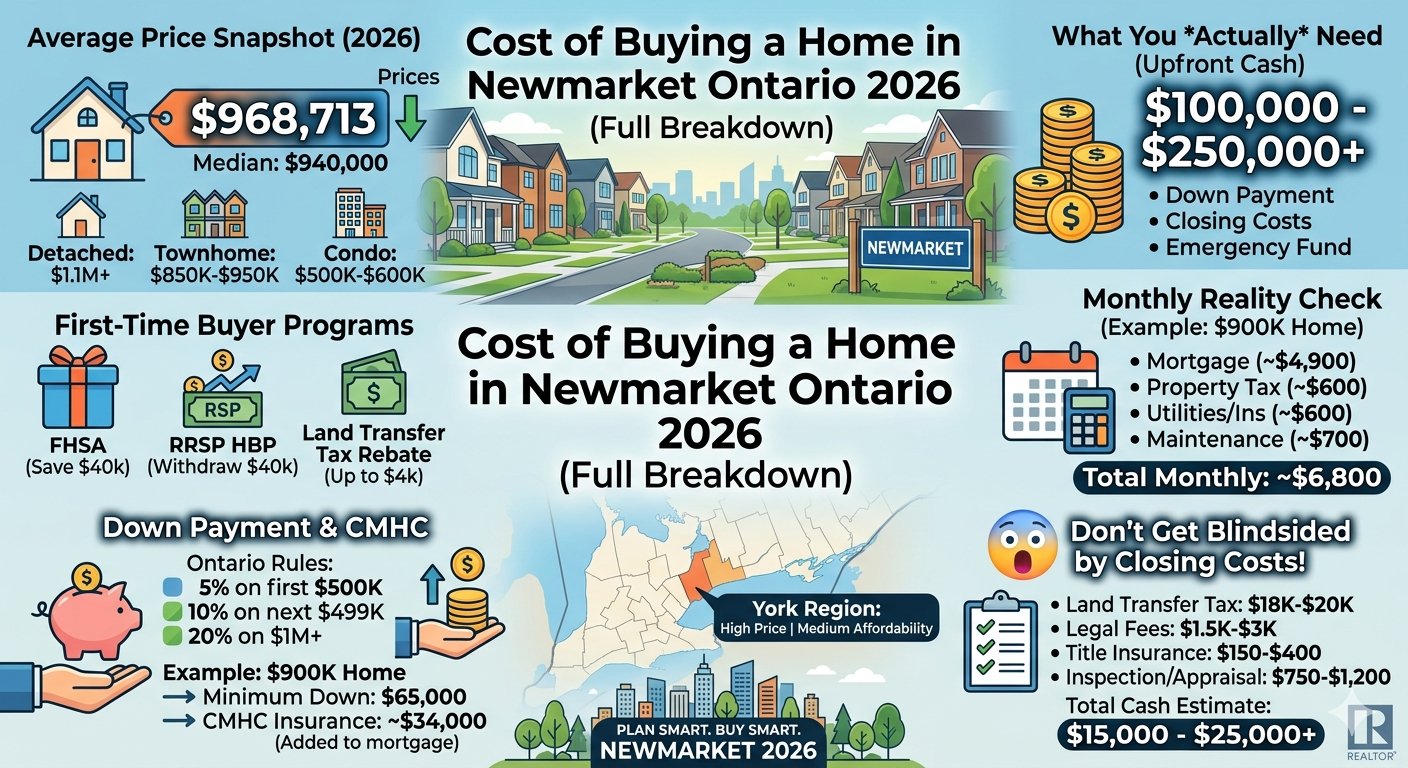
If you're buying a typical home in Newmarket in 2026, expect to have $100,000–$250,000 in total upfront cash ready — depending on property type, your down payment, and whether you qualify for first-time buyer programs. That's not fear-mongering. That's math.
Newmarket Home Prices: 2026 Market Snapshot
Newmarket sits in York Region, just north of Toronto — close enough to command premium prices, far enough to still attract buyers who've been priced out of the city. Here's where the market actually stands heading into 2026:
| Property Type | Price Range | Best For |
|---|---|---|
| Condo Apartment | $490K–$600K | First-time buyers, investors |
| Townhome | $850K–$950K | Move-up buyers, small families |
| Detached | $1.1M–$1.3M+ | Families, upgraders |
Prices dipped about 7.8% year-over-year — down from roughly $1.02M in March 2025 to $940,000 median in March 2026. But don't get too excited. They're still firmly in "this requires serious planning" territory, with a monthly rebound of ~5.6% from February 2026 already signalling stabilization.
Not sure what you can actually afford?
Get a personalized budget strategy — not a generic calculator. Deepak Raj will walk you through exactly what you can realistically afford in Newmarket based on your income, savings, and timeline.
📅 Book Your Free Strategy Call First-Time Buyer Guide →Down Payment Rules for Ontario Buyers (2026)
Ontario follows national down payment rules under the Financial Consumer Agency of Canada. The breakdown is tiered — and it catches a lot of buyers off guard when they realize 5% doesn't go as far as they thought.
5% on the first $500,000 | 10% on $500,001–$999,999 | 20% on $1,000,000+
Example: $900,000 Home in Newmarket
| Component | Amount | Notes |
|---|---|---|
| 5% on first $500K | $25,000 | Required minimum |
| 10% on next $400K | $40,000 | Required minimum |
| Total Down Payment | $65,000 | Minimum to enter |
| Mortgage Amount | ~$835,000 | Before CMHC added |
| CMHC Insurance (~4% of mortgage) | ~$34,000 | Added to mortgage, not upfront |
CMHC mortgage default insurance (required below 20% down) quietly adds $34,000+ to your mortgage balance on a $900K home. You don't pay it at closing — but you're paying interest on it for the next 25 years.
Closing Costs in Newmarket Ontario — The Full List
This is where buyers get blindsided. Closing costs typically run 3%–5% of the purchase price in Ontario — that's $27,000–$45,000 on a $900K home. After first-time buyer rebates, most buyers end up with a net bill of $15,000–$25,000 in extra cash on top of the down payment.
| Cost Item | Estimated Cost | Notes |
|---|---|---|
| Ontario Land Transfer Tax | $18,000–$20,000 | Calculated on purchase price |
| Legal Fees & Disbursements | $1,500–$3,000 | Higher for complex titles |
| Title Insurance | $150–$400 | Typically required by lender |
| Home Inspection | $450–$700 | For detached in Newmarket |
| Mortgage Appraisal | $300–$500 | If required by lender |
| First-Time Buyer LTT Rebate | −$4,000 | Up to $4K back on LTT |
| Total After Rebates | $15,000–$25,000 | Additional cash beyond down payment |
Land Transfer Tax Explained
Ontario's Land Transfer Tax is calculated on a tiered bracket system. On a $900,000 home, a non-first-time buyer pays approximately $18,000–$20,000. First-time buyers receive up to a $4,000 rebate — effectively paying $0 LTT on the first ~$368,333 of the purchase price.
Real Monthly Costs of Owning a Home in Newmarket
The mortgage payment is only part of the story. Here's what a $900,000 home actually costs per month in 2026 — the number you need to know before you fall in love with a listing:
Monthly Carrying Costs — $900K Home Example
That's the real number. Not the one people casually throw around at dinner parties. And it assumes a 10% down payment — if you go in at the minimum 5%, your mortgage payment and CMHC premiums push this even higher.
Hidden Costs Nobody Warns You About
These are the silent budget killers that hit in the first 6–12 months. Smart buyers budget 5%–10% extra beyond purchase costs to cover these.
First-Time Buyer Programs That Actually Help (2026)
These programs don't make homes cheap. They make them possible. Here's what's available for first-time buyers in Ontario in 2026:
First Home Savings Account (FHSA)
Save up to $40,000 tax-free with tax-deductible contributions specifically for your first home purchase.
Learn More →RRSP Home Buyers' Plan
Withdraw up to $40,000 from your RRSP tax-free (to be repaid over 15 years) toward your down payment.
Learn More →Ontario LTT Rebate
Up to $4,000 back on land transfer tax as a first-time buyer — effectively $0 LTT on the first $368K.
Learn More →Zero Down Program
Ask Deepak about our Zero Down Program — a strategy to help qualified buyers enter the market sooner.
See if You Qualify →Rent-to-Own Program
Not quite ready to buy outright? Rent-to-own builds equity while you save — a real path to ownership.
Explore Program →Buy With Zero Down or Rent-to-Own — Let's Talk
If you don't have $100K+ sitting in a savings account right now, that doesn't mean homeownership is off the table. Deepak Raj has helped buyers get into the market using programs most people don't even know exist.
🏠 Book: Zero Down & Rent-to-Own ConsultationTotal Upfront Cost: Full $900K Example
| Category | Amount | How It's Paid |
|---|---|---|
| Minimum Down Payment (5%) | $45,000 | Upfront at closing |
| Land Transfer Tax (after rebate) | ~$14,000–$18,000 | Upfront at closing |
| Legal Fees | ~$2,000 | Upfront at closing |
| Title Insurance | ~$300 | Upfront at closing |
| Home Inspection | ~$600 | Before offer/closing |
| Appraisal (if required) | ~$400 | Pre-closing |
| CMHC Insurance (~4%) | ~$34,000 | Added to mortgage |
| Total Cash at Closing (excl. CMHC) | ~$62,000–$66,000 | Cash required on closing day |
Plus your moving costs, first-year maintenance budget, and emergency fund — and you're looking at a realistic total preparation figure of $80,000–$100,000+ for a $900K home. That's why the headline range is $100K–$250K. The higher end applies to detached homes above $1.1M with 10–20% down.
How Newmarket Compares to GTA & Surrounding Areas
York Region sits in that awkward middle — not Toronto expensive, but definitely not beginner-friendly either. Here's where Newmarket fits in the broader Ontario landscape:
Buyer Strategy by Type
🏠 First-Time Buyers
Best entry point in Newmarket is condos ($500K–$600K) or townhomes ($850K–$950K). Stack your FHSA + RRSP HBP + LTT rebate to reduce cash required. Focus on monthly affordability, not just sticker price — the mortgage is one of five recurring costs you'll carry.
🔑 Move-Up Buyers
Leverage existing equity from your current property. Watch interest rate cycles carefully — a rate hold or cut before your renewal can change your math significantly. Consider a bridge loan strategy if timing your sale and purchase simultaneously.
📈 Investors
Condo market remains the accessible entry point for investment. Rental demand in Newmarket is strong, driven by its proximity to Toronto and growing employment base. Cash flow is tighter with current rates — smart investors are prioritizing long-term appreciation and quality tenants over short-term cash flow speculation.
Frequently Asked Questions
How much money do I need to buy a house in Newmarket Ontario in 2026?
Realistically, plan for $100,000–$250,000 in total upfront cash, depending on property type and down payment amount. For a $900K townhome with minimum 5% down, you're looking at roughly $62,000–$66,000 at closing (not counting CMHC which is added to mortgage), plus another $15,000–$20,000 for first-year expenses. For a $1.1M+ detached home with 20% down, that number climbs to $220,000+.
What are closing costs in Newmarket Ontario?
Closing costs in Newmarket typically run $15,000–$25,000 in additional cash beyond your down payment (after first-time buyer rebates, if applicable). The biggest item is Ontario Land Transfer Tax (~$18,000–$20,000 on a $900K home), followed by legal fees ($1,500–$3,000), title insurance ($150–$400), home inspection ($450–$700), and appraisal ($300–$500).
Can I buy a home in Newmarket with only 5% down in 2026?
Yes — for homes priced under $1,000,000, you can put as little as 5% down on the first $500K and 10% on the remaining balance. But you'll be required to carry CMHC mortgage default insurance, which adds approximately $34,000 to your mortgage balance on a $900K purchase. You don't pay this upfront, but you pay interest on it for the life of your mortgage.
What is the average monthly cost to own a home in Newmarket in 2026?
For a typical $900K home in Newmarket, expect to pay approximately $6,800 per month in total carrying costs: mortgage (~$4,900), property taxes (~$600), utilities and home insurance (~$600), and a maintenance reserve (~$700). This is based on a 25-year amortization at approximately 5.25% interest.
Are home prices going up or down in Newmarket in 2026?
Prices are slightly down year-over-year — the median home price dropped about 7.8% from $1.02M in March 2025 to $940,000 in March 2026. However, month-over-month the market is already rebounding, up approximately 5.6% from February 2026. The overall trend is stabilization, not continued decline.
What first-time buyer programs are available in Ontario in 2026?
The main programs available are: First Home Savings Account (FHSA) — save up to $40,000 tax-free; RRSP Home Buyers' Plan — withdraw up to $40,000 tax-free; Ontario Land Transfer Tax Rebate — up to $4,000 back; and CMHC insured mortgages allowing 5% entry. Additionally, ask about the Zero Down Program and Rent-to-Own Program available through PrimeHomes.ca.
Ready to Buy Smart in Newmarket in 2026?
Stop guessing. Get a clear, personalized breakdown of what you can actually afford — including access to off-market opportunities, zero down programs (if you qualify), and a strategy built around your numbers.
📞 Book Your Free Consultation with Deepak Raj

 Data provided by the Ontario Regional Technology & Information Systems. The information is deemed reliable, but is not guaranteed. Not intended to solicit buyers or sellers, landlords or tenants currently under contract.
The trademarks REALTOR®, REALTORS® and the REALTOR® logo are controlled by The Canadian Real Estate Association (CREA) and identify real estate professionals who are members of CREA. The trademarks MLS®, Multiple Listing Service® and the associated logos are owned